“Nobody can predict interest rates, the future direction of the economy or the stock market. Dismiss all such forecasts and concentrate on what's actually happening to the companies in which you've invested."
— Peter Lynch
In the third quarter, attention shifted away from the AI trade as macroeconomic themes and geopolitical worries reemerged as key market drivers. Concerns over rising Treasury yields, elevated oil prices, and the potential start of a Fed rate-hiking cycle slowed the small-stock resurgence that had been gaining momentum. For the quarter, the Russell 2000® Value Index sank 4.91%, compared to the 2.30% gain for the S&P 500.
However, it’s important to keep a few things in perspective. For starters, we agree with Peter Lynch that it’s futile to try and forecast the direction of interest rates and other macro factors in hopes of predicting short-term market behavior. For us, our time is better spent analyzing the companies we own or assessing potential new investments to consider. Put another way, bottom-up research trumps top-down theories.
Also, if we’ve learned anything this year, it’s that three months doesn’t make a trend. While small stocks lagged in the quarter, the Russell 2000® Value is still outperforming the S&P 500 on a year-to-date basis, 16.96% versus 12.75%. In addition, the backdrop for value investing is improving. Rising interest rates, which have been viewed as a potential headwind for small caps, are starting to force investors to think more about valuations as equities face stiffer competition for investment dollars.
The good news is that small caps continue to enjoy a sizeable valuation advantage over large stocks. As the chart below shows, the S&P Small Cap 600 Index, using consensus Price/Earnings ratios for the next twelve months, is trading at a substantial discount to the S&P 500.
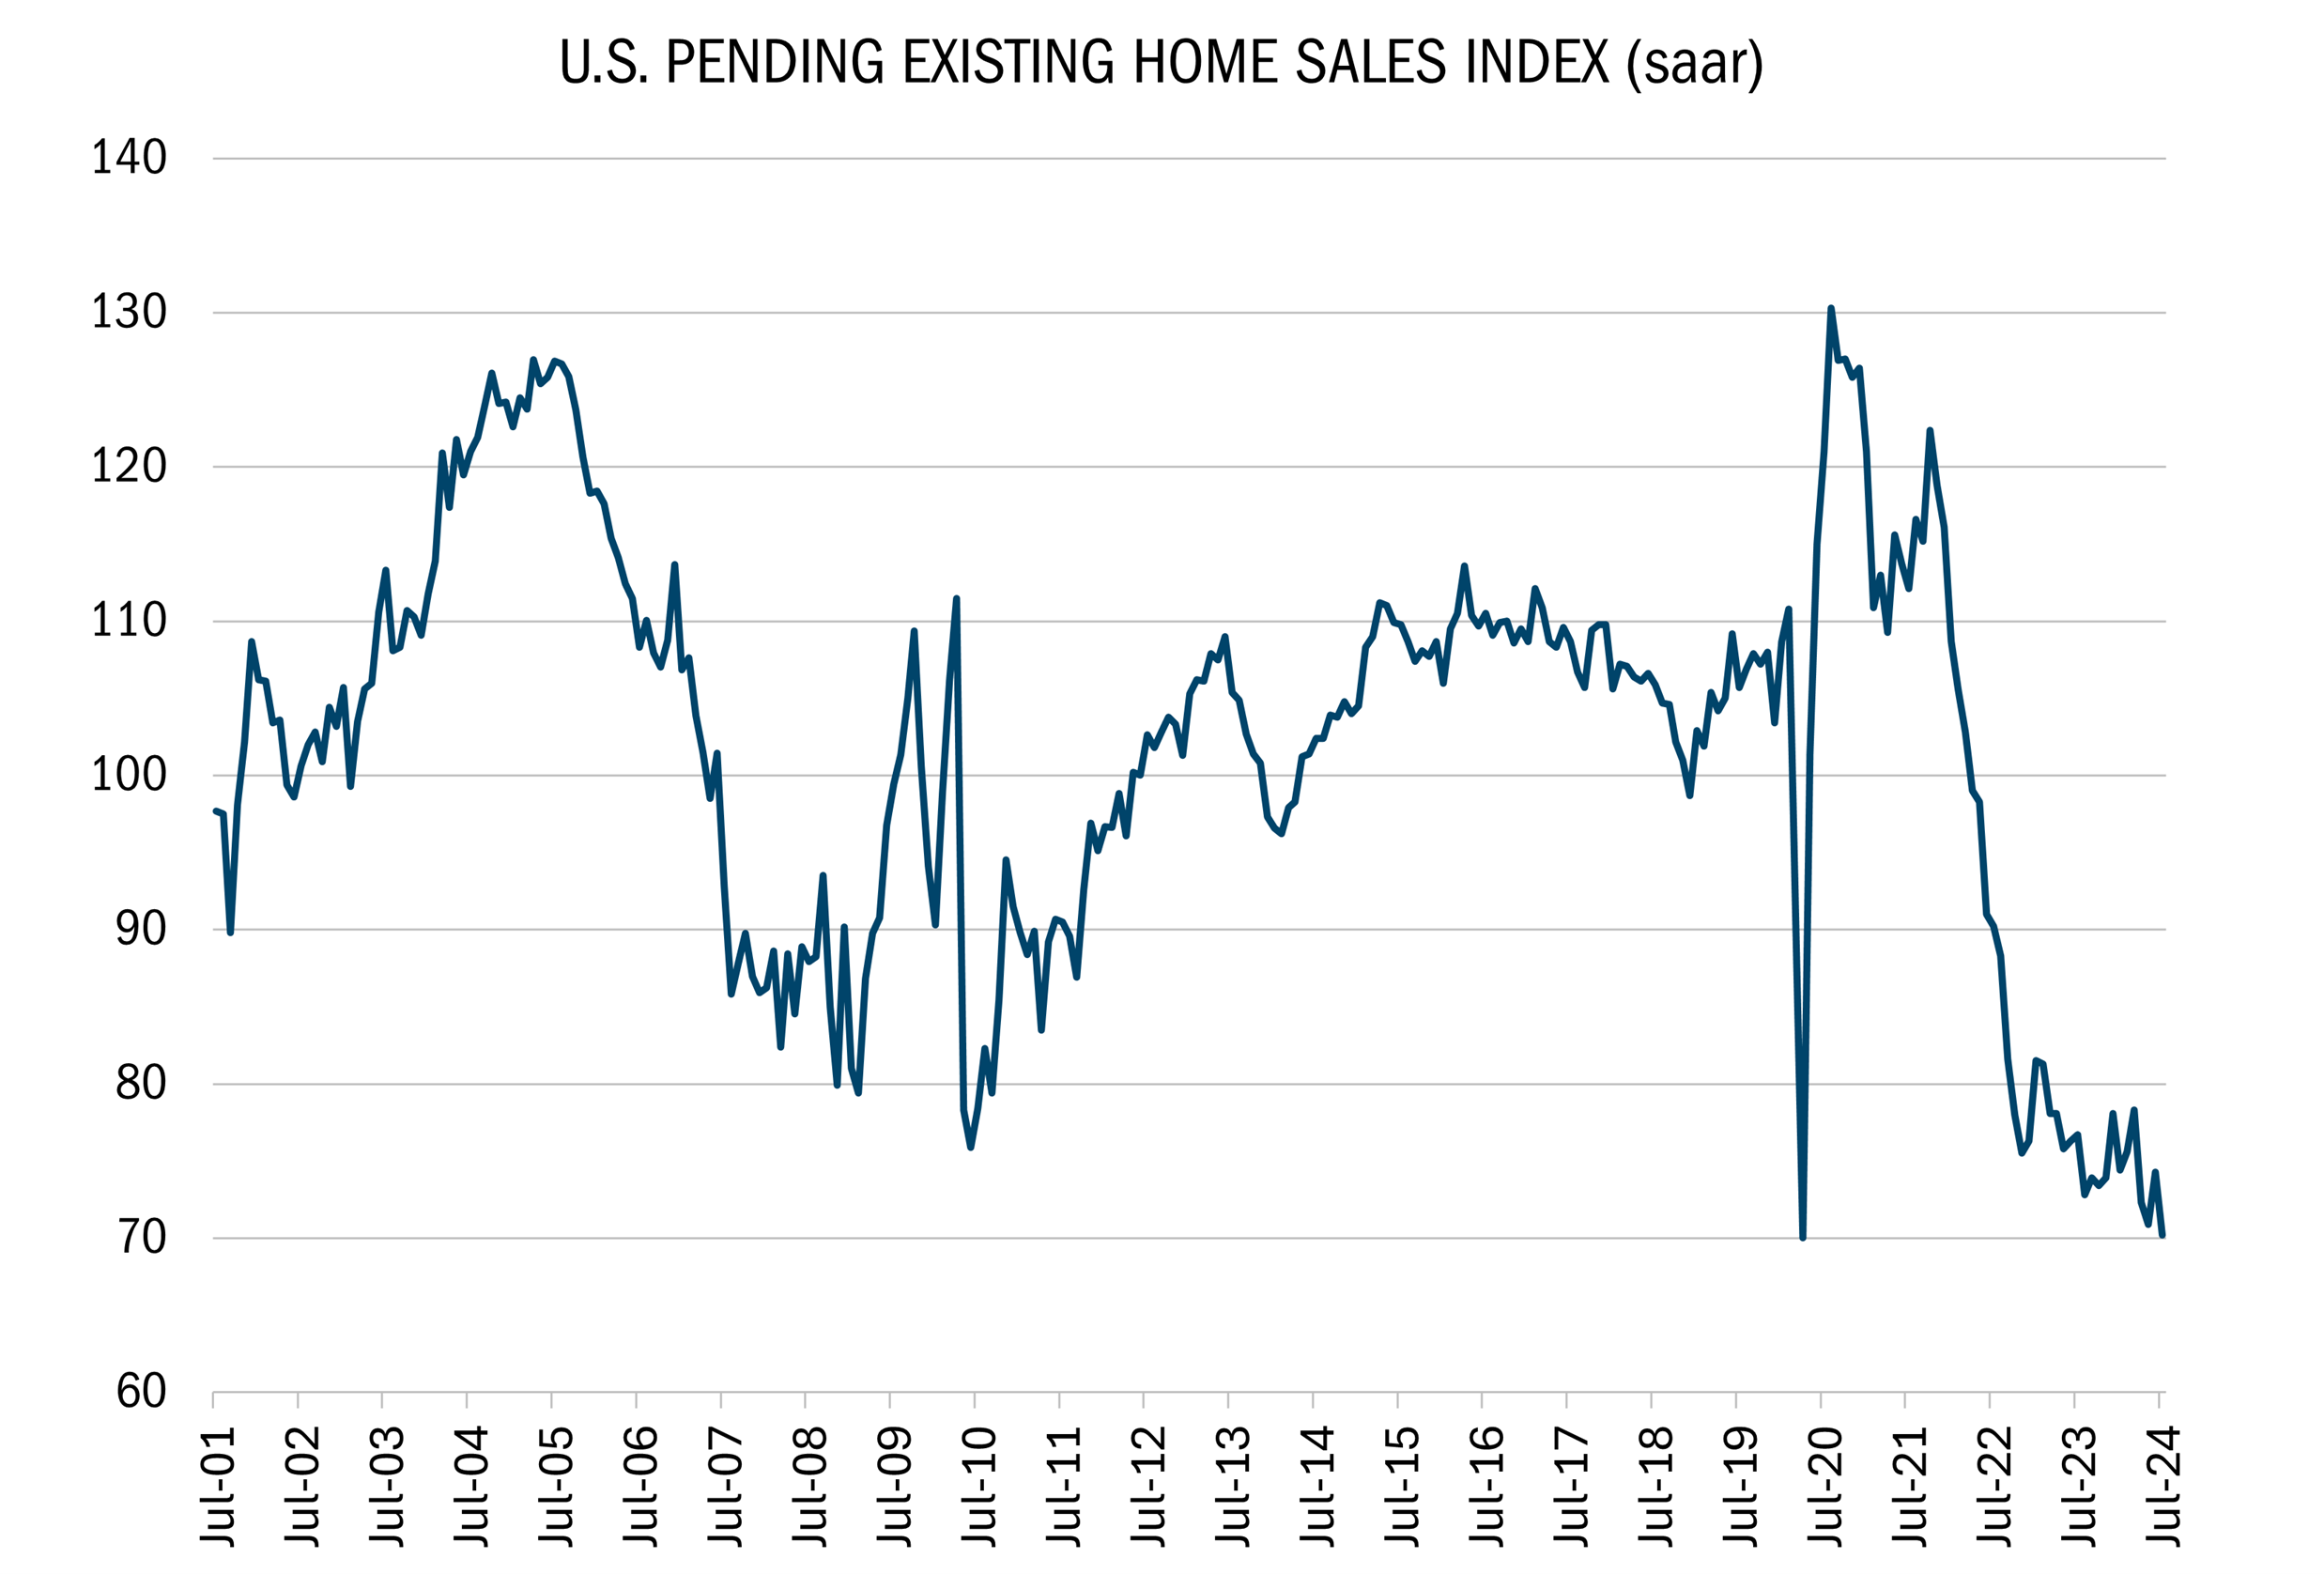
Source: FactSet Research Systems, Inc., Monthly data 7/31/2001 to 9/29/2026. This chart represents the comparison of the NTM P/E (next twelve-month price to earnings) for the S&P 600 Index versus the S&P 500 Index. S&P 500 Index is an index of 500 U.S. stocks chosen for market size, liquidity and industry group representation and is a widely used U.S. equity benchmark. S&P 600 Index is an index of small-cap stocks managed by Standard & Poor's. All indices are unmanaged. It is not possible to invest directly in an index. All indices are unmanaged. It is not possible to invest in an index. Past performance does not guarantee future results.
Importantly, the Strategy trades at only 10X the next twelve months’ profits, for an earnings yield (the inverse of the price/earnings ratio) of 10%. That’s compared to the 5.2% on 10-Year Treasuries and the 6-7% payout for corporate bonds. By contrast, the S&P 500 is at 5.3%. This creates a favorable environment for active, valuation driven small-cap investors. In our opinion, we are well positioned to take advantage of market disparities because of our adherence to the 10 Principles of Value Investing™, which requires that fundamental factors such as strong balance sheets, profitable growth, and attractive valuations drive all of our portfolio decisions.
We’re mindful that the market continues to be fickle and unpredictable. We’ve been doing this long enough to understand this renewed focus on fundamentals may not persist. This is why a key element of our approach is to plan for a wide range of potential outcomes. For every investment we hold or consider owning, we establish four separate price targets: a base case, an upside scenario, a downside development, and a max loss circumstance associated with severe business stress. This approach is as useful to us now, after our benchmark hit a speedbump during the quarter, as it was earlier in the year, when investors’ appetite for small stocks rebounded sharply.
In the third quarter, the Heartland Small Cap Value Strategy fell 6.62%, compared to the 4.91% loss for the Russell 2000® Value Index. Security selection was mixed, with positive effects in Materials, Financials, and Utilities but negative results in Energy, Industrials, and Consumer Discretionary.
Within Energy, part of our underperformance was based on what we don’t own—we are under-exposed to pure-play refiners, which have recently been among the market’s best performers. In Industrials, a few holdings were impacted by the AI trade, as companies that were viewed as winners of the data center buildout earlier in the year were punished in the period, as AI interest waned.
Against this backdrop, it seems prudent to take what the market is giving us while derisking some positions that saw rapid appreciation earlier in the year. It also makes sense to focus on what we do best: identifying well-run businesses priced well below their intrinsic worth. In the third quarter, one of our companies was taken private, bringing the total number of holdings acquired in 2026 to seven. We view this as validation of our disciplined investment process.
One of our holdings receiving strategic interest is a leading global medical device contract development and manufacturing organization (CDMO). A year ago, the stock sank more than 30% after reporting disappointing results and lowering guidance for growth and margin expansion this year. Yet bolstered by our research and insider buying we remained confident in the business. Also at year-end, a significant investor built a stake in the company and urged management to explore a sale. In the third quarter, an acquirer agreed to buy the company for $127 a share, which was in line with our target price and represented a greater than 70% premium to our average cost.
A good example of our focus on valuations—and the value of active management—is Academy Sports and Outdoors (ASO). In the summer, we added to our position in this $6 billion in sales retailer, after rival Dick’s Sporting Goods missed badly on its second quarter earnings. That news sent the whole group down.
But Dick’s issues stemmed largely from its footwear business, and shoes represent a much smaller portion of Academy’s business. At the same time, ASO has meaningful exposure to outdoor recreation, a category that’s begun to pick up following years of weakness. There are also company-specific catalysts to drive improvement such as revamping of its e-commerce business, launching a new credit card, growing its loyalty program, and continuing to expand merchandising for higher income consumers.
In September, the stock surged after Academy reported Q2 results that were stronger than investors had feared. Despite this, ASO is valued at just 7X this year’s earnings and 7X next. Giving us even more confidence is management’s use of strong free cash flow to repurchase 40% of ASO shares outstanding since Academy went public in 2020.
A recently added holding is Hillman Solutions (HLMN). If you walk into your favorite hardware store and go to the fasteners aisle for items such as nuts, screws, and bolts, there’s a high likelihood it was manufactured, supplied, and managed by Hillman. Fasteners are an important section of any home-improvement store because they drive traffic. Yet they are complex to manage due to the high number of individual items. Hillman has a team of dedicated associates that work with retailers to keep shelves inventoried and presentable, thus creating sticky partnerships and higher margins.
High interest rates have depressed demand for home repairs and remodeling among Hillman’s core customer, the do-it-yourself crowd. Foot traffic at Lowe’s and Ace Hardware—HLMN’s top two retailers—have been choppy as well, weighing on its stock price.
While it is hard to know when interest rates will be more favorable or when repair and remodel demand will improve, Hillman is driving growth in other areas, which should help it stand out versus its peers. HLMN, for instance, recently launched a new emphasis on top customers in the Pro channel, an opportunity which could drive 1-2% of annual top-line growth. Additionally, management made an acquisition that gives them a beachhead to expand in the Industrial fastener space.
The stock currently trades at less than 6.5X next year’s EBITDA, well below distributors in the Industrial sector. In fact, over the past two decades, Hillman has been sold to private equity firms twice, at 10-11X EBITDA. We forecast HLMN can achieve similar pricing once housing demand improves and management executes on the organic growth opportunities.
If there ever was a time for active management, this is it. While the past three months may have been challenging for our part of the market, the underlying backdrop for disciplined stock-picking has noticeably improved. As rates have risen and competition for investment dollars has grown, investors now care more about fundamentals and valuations. This is creating potential risk-versus-reward opportunities for our Strategy. It’s important to recognize, though, that not all companies in our benchmark are poised to outperform. This is why our 10 Principles of Value Investing™ are crucial to identifying fundamentally sound and attractively priced businesses with growth potential. We are excited about what lies ahead.
Fundamentally yours,
The Heartland Investment Team
9/30/2026
Scroll over to view complete data
| Since Inception (%) | 10-Year (%) | 5-Year (%) | 3-Year (%) | 1-Year (%) | YTD (%) | QTD (%) | |
|---|---|---|---|---|---|---|---|
| Small Cap Value Composite (Net of Advisory Fees)** | 11.46 | 10.50 | 13.87 | 24.46 | 16.77 | 13.34 | -6.57 |
| Small Cap Value Composite (Net of Bundled Fees) | 10.06 | 10.19 | 13.57 | 24.17 | 16.54 | 13.17 | -6.62 |
| Russell 2000® Value | 10.26 | 9.40 | 7.80 | 17.93 | 20.77 | 16.96 | -4.91 |
Source: FactSet Research Systems Inc., Russell Investment Group, and Heartland Advisors, Inc.
*Yearly and quarterly returns are not annualized. The Strategy's inception date is 10/1/1988.
**Shown as supplemental information.
The US Dollar is the currency used to express performance. Returns are presented net of advisory fees and net of bundled fees and include the reinvestment of all income. The returns net of bundled fees were calculated by subtracting the highest applicable sponsor portion of the separately managed wrap account fee from the net of advisor fees return.


©2026 Heartland Advisors | 790 N. Water Street, Suite 1200, Milwaukee, WI 53202 | Business Office: 414-347-7777 | Financial Professionals: 888-505-5180 | Individual Investors: 800-432-7856
Past performance does not guarantee future results.
The Small Cap Value Strategy seeks long-term capital appreciation by investing in micro- and small-cap companies, generally with market capitalizations of less than the largest companies in the Russell 2000 Value Index, at the time of purchase. The micro- and small-cap segment of the stock market is robust with thousands of publicly traded issues, many of which lack traditional Wall Street research coverage. Thus, we believe this market is often inefficient, mispricing businesses and offering opportunities for fundamental research-minded investors such as Heartland.
The Small Cap Value Strategy invests in small companies selected on a value basis. Such securities generally are more volatile and less liquid than those of larger companies.
Value investments are subject to the risk that their intrinsic values may not be recognized by the broader market.
Heartland Advisors, Inc. (the “Firm”) claims compliance with the Global Investment Performance Standards (GIPS®). The Firm is a wholly owned subsidiary of Heartland Holdings, Inc. and is registered with the Securities and Exchange Commission. For a complete list and description of Heartland Advisors composites and/or a presentation that adheres to the GIPS® standards, contact Institutional Sales at Heartland Advisors, Inc. at the address listed below.
As of 9/30/2026, Academy Sports and Outdoors, Inc. (ASO) and Hillman Solutions Corporation (HLMN), represented 4.38% and 1.03% of the Small Cap Value Composite’s net assets, respectively. DICK'S Sporting Goods, Inc. (DKS) is unowned by Heartland Advisors, Inc.
The future performance of any specific investment or strategy (including the investments discussed above) should not be assumed to be profitable or equal to past results. The performance of the holdings discussed above may have been the result of unique market circumstances that are no longer relevant. The holdings identified above do not represent all of the securities purchased, sold or recommended for the Advisor’s clients.
Portfolio holdings are subject to change. Current and future portfolio holdings are subject to risk.
Statements regarding securities are not recommendations to buy or sell.
In certain cases, dividends and earnings are reinvested.
GIPS® is a registered trademark of CFA Institute. CFA Institute does not endorse or promote this organization, nor does it warrant the accuracy or quality of the content contained herein.
Separately managed accounts and related investment advisory services are provided by Heartland Advisors, Inc., a federally registered investment advisor. ALPS Distributors, Inc., is not affiliated with Heartland Advisors, Inc.
The statements and opinions expressed in this article are those of the presenter(s). Any discussion of investments and investment strategies represents the presenters’ views as of the date created and are subject to change without notice. The opinions expressed are for general information only and are not intended to provide specific advice or recommendations for any individual. The specific securities discussed, which are intended to illustrate the advisor’s investment style, do not represent all of the securities purchased, sold, or recommended by the advisor for client accounts, and the reader should not assume that an investment in these securities was or would be profitable in the future. Certain security valuations and forward estimates are based on Heartland Advisors’ calculations. Any forecasts may not prove to be true.
Economic predictions are based on estimates and are subject to change.
There is no guarantee that a particular investment strategy will be successful.
Sector and Industry classifications are sourced from GICS®.The Global Industry Classification Standard (GICS®) is the exclusive intellectual property of MSCI Inc. (MSCI) and S&P Global Market Intelligence (“S&P”). Neither MSCI, S&P, their affiliates, nor any of their third party providers (“GICS Parties”) makes any representations or warranties, express or implied, with respect to GICS or the results to be obtained by the use thereof, and expressly disclaim all warranties, including warranties of accuracy, completeness, merchantability and fitness for a particular purpose. The GICS Parties shall not have any liability for any direct, indirect, special, punitive, consequential or any other damages (including lost profits) even if notified of such damages.
Heartland Advisors defines market cap ranges by the following indices: micro-cap by the Russell Microcap®, small-cap by the Russell 2000®, mid-cap by the Russell Midcap®, large-cap by the Russell Top 200®.
Because of ongoing market volatility, performance may be subject to substantial short-term changes.
Dividends are not guaranteed and a company’s future ability to pay dividends may be limited. A company currently paying dividends may cease paying dividends at any time.
There is no assurance that dividend-paying stocks will mitigate volatility.
Russell Investment Group is the source and owner of the trademarks, service marks and copyrights related to the Russell Indices. Russell® is a trademark of the Frank Russell Investment Group.
Data sourced from FactSet: Copyright 2026 FactSet Research Systems Inc., FactSet Fundamentals. All rights reserved.
Heartland’s investing glossary provides definitions for several terms used on this page.
Artificial intelligence (AI) is intelligence—perceiving, synthesizing, and inferring information—demonstrated by computers, as opposed to intelligence displayed by humans or by other animals. Earnings Per Share is the portion of a company’s profit allocated to each outstanding share of common stock. Free Cash Flow is the amount of cash a company has after expenses, debt service, capital expenditures, and dividends. The higher the free cash flow, the stronger the company’s balance sheet. NASDAQ is a global electronic marketplace for buying and selling securities, as well as the benchmark index for U.S. technology stocks. NASDAQ was created by the National Association of Securities Dealers (NASD) to enable investors to trade securities on a computerized, speedy and transparent system, and commenced operations on February 8, 1971. Net Margin is the ratio of net profits to revenues for a company or business segment - typically expressed as a percentage – that shows how much of each dollar earned by the company is translated into profits. Price/Earnings Ratio of a stock is calculated by dividing the current price of the stock by its trailing or its forward 12 months’ earnings per share. Russell Investment Group is the source and owner of the trademarks, service marks and copyrights related to the Russell Indices. Russell® is a trademark of the Russell Investment Group. Russell 2000® Index includes the 2000 firms from the Russell 3000® Index with the smallest market capitalizations. All indices are unmanaged. It is not possible to invest directly in an index. Russell 2000® Value Index measures the performance of those Russell 2000® companies with lower price/book ratios and lower forecasted growth characteristics. All indices are unmanaged. It is not possible to invest directly in an index. Volatility is a statistical measure of the dispersion of returns for a given security or market index which can either be measured by using the standard deviation or variance between returns from that same security or market index. Commonly, the higher the volatility, the riskier the security. 10 Principles of Value Investing™ consist of the following criteria for selecting securities: (1) catalyst for recognition; (2) low price in relation to earnings; (3) low price in relation to cash flow; (4) low price in relation to book value; (5) financial soundness; (6) positive earnings dynamics; (7) sound business strategy; (8) capable management and insider ownership; (9) value of company; and (10) positive technical analysis.