The U.S. equity market remained resilient through much of the third quarter, supported by strong second-quarter corporate profit growth despite rising energy prices related to the conflict in Iran. Equities weakened beginning in late August as interest rates rose sharply. The U.S. 10-year Treasury yield was 5.3% at quarter end, the highest rate since 2007, and the real yield (nominal yield less inflation) rose to 2.9%, the highest level since 2008.
The third quarter also highlighted sharp divergence between major indexes. After surging in the second quarter, many semiconductor stocks retreated as enthusiasm surrounding parts of the AI trade began to waver. Meanwhile, hopes for Fed rate cuts at the start of the year gave way to concerns about renewed tightening. As a result, the Russell 2000® Index fell 4.91% over the past three months, while the S&P 500 gained 2.30% aided by double-digit percentage gains in several multi-trillion dollar companies including Microsoft, NVIDIA, Apple and Meta.
But while stock prices are oscillating on ebbing and flowing news, the intrinsic value of those underlying businesses is not moving nearly as much. For example, Microsoft rose more than 35% in the third quarter while the consensus estimates for 2027 and 2028 operating profit increased less than 3%. How could the value of a blue-chip company worth more than $3 trillion move in such an extreme way? The answer comes down to expectations and valuation. Earlier, from November 2025 through June 2026, shares of Microsoft fell by roughly 35% despite modest increases in those same profit estimates. The magnitude of stock price volatility was therefore driven less by changes in expected earnings than by changing perceptions of whether Microsoft was a loser or a winner from the proliferation of AI. Among smaller companies, these narrative-driven swings can be even more pronounced.
We continue to believe AI is very real; however, history suggests that capital cycles can front run the economic returns ultimately generated by the technology. The sharp rise in public and private financing for AI infrastructure suggests that possibility deserves careful consideration. We believe corporate profit growth remains at historically strong levels, thanks to elevated margins and the tailwinds created by the massive capex spending tied to the data center buildout. As the chart below shows, the 10-year S&P 500 earnings growth rate now stands above the level seen in the Dotcom era and is approaching post-WWII record highs.
Corporates are over-earning: one of the strongest EPS cycles in history
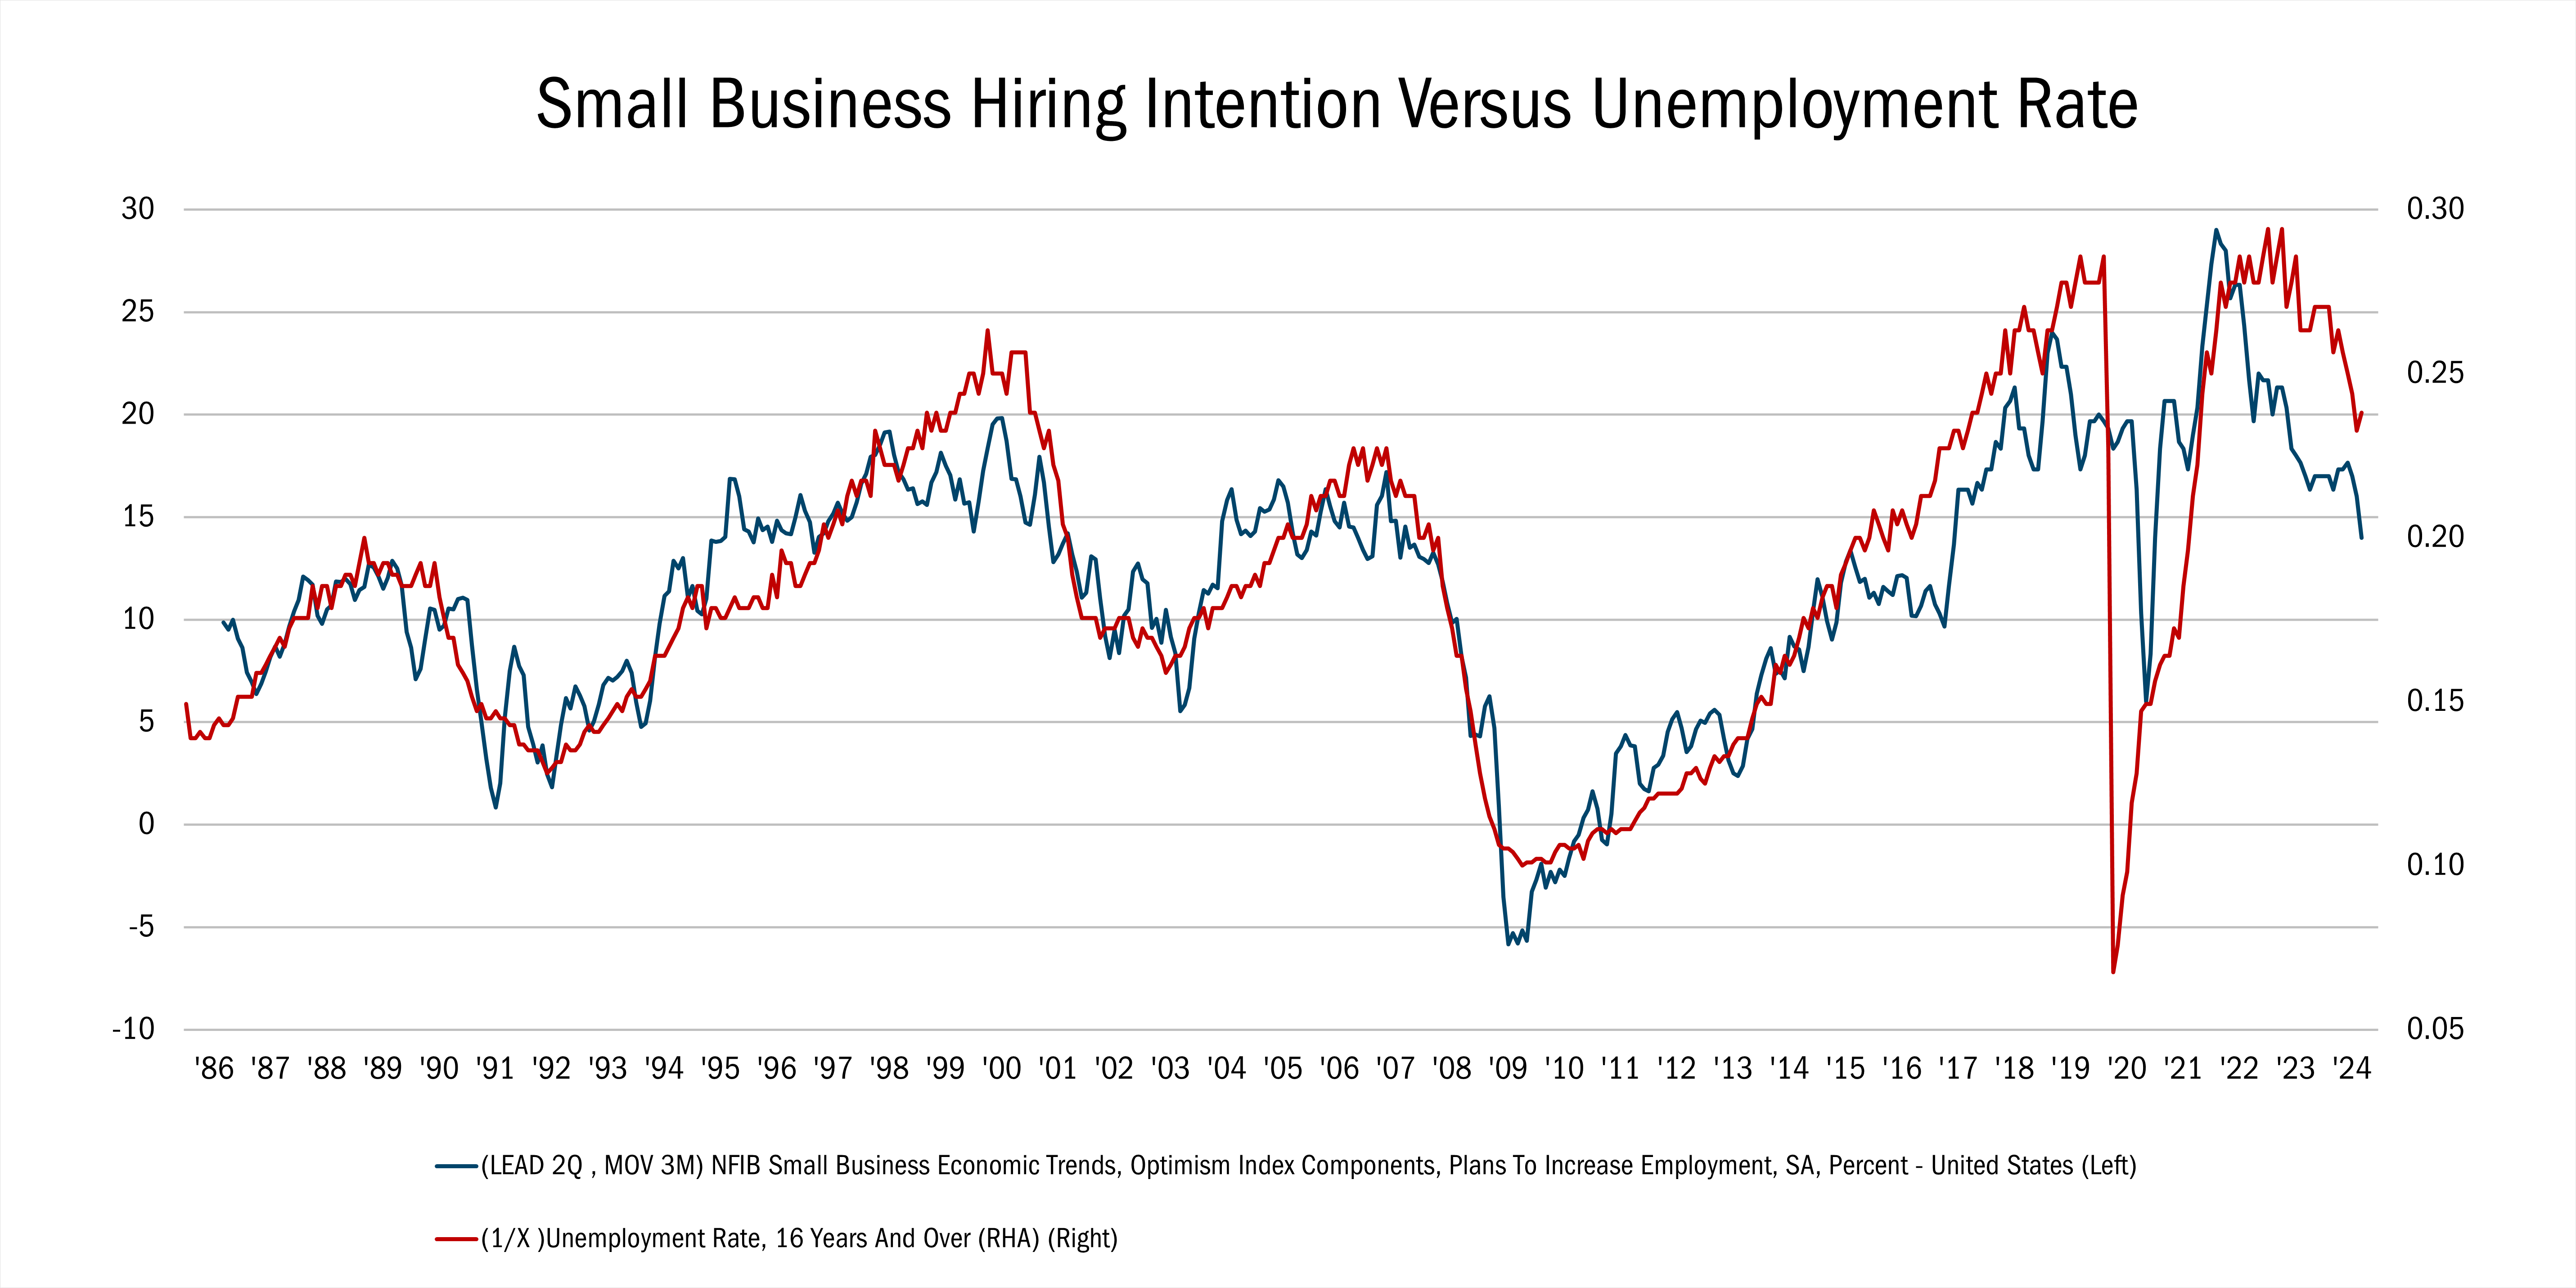 Source: Wells Fargo Securities. Monthly data from January 1881 to September 2026. This chart represents the ten-year growth rate of the S&P 500 earnings per share (EPS) compared with a long-term NTM (next-twelve-month) earnings growth forecast. Earnings Per Share is the portion of a company’s profit allocated to each outstanding share of common stock. S&P 500 Index is an index of 500 U.S. stocks chosen for market size, liquidity and industry group representation and is a widely used U.S. equity benchmark. All indices are unmanaged. It is not possible to invest directly in an index. All indices are unmanaged. It is not possible to invest in an index. Past performance does not guarantee future results.
Stepping back, fewer than ten public companies are poised to spend about $1 trillion of capital on technology infrastructure in 2026, which would boost GDP by about 3% alone. These same companies are forecasted to spend $1.3 trillion in 2027. However, this data excludes certain operating leases that don’t qualify as capex per accounting standards, but the leases are being guaranteed by the tenant, which unlocks additional financing to fund the capital cycle.
Companies may be ‘over-earning’ because of the front-loaded nature of the AI investment cycle. On the one hand, positive drivers of earnings are often realized upfront. Financial intermediaries recognize fees as capital is raised, while equipment suppliers, contractors, semiconductors manufacturers, and optical connectivity providers, among many others, benefit from extreme pricing power as the capital is deployed. In contrast, much of the cost to hyperscalers is recognized later because depreciation begins only after assets are placed in service, and they are expensed over their useful lives. The result is a timing mismatch with many of the earnings benefits appearing early in the cycle, while some of the associated costs emerge later.
This does not mean the AI capex boom is certain to peak anytime soon. Using a baseball analogy, a capital cycle bubble does not pop in the ninth inning. It bursts in extra innings. Whether the game lasts ten, twelve, or more innings is anyone’s guess, but a classic indicator that we’re late in the game can be found in the rising dependence on third party capital to fund marginal capex growth. In addition, Wall Street is relying on a few critical assumptions to add leverage to the mix including the idea that a new chip architecture won’t render existing infrastructure quickly obsolete and/or that none of the large capital spenders of today ultimately fail despite many of the top spenders, both public and private, generating negative free cash flow. Current valuations in parts of the market appear to assume that unusually high returns can persist despite the competitive response those returns are likely to attract.
As a capital market bubble approaches the crescendo, even the bulls recognize that excesses are unsustainable, but market speculators assume they’ll be able to sell before the bubble bursts. The problem with this concept is that many of the same firms publishing forecasts that predict abnormal growth far into the future are the same firms earning fees from capital raising efforts. Their incentive is not to let the world know when the cycle is over. Rather, they’re incentivized to raise as much capital as quickly as possible. For this reason, it’s important for investors who think like business owners to consider all possible tailwinds and headwinds that could impact a company’s cash flows, which in turn will impact their assessment of intrinsic value. This is why it’s so important to plan for a range of potential outcomes.
At Heartland, we address uncertainty by evaluating a range of potential outcomes for every business we hold or consider owning. Our research incorporates base, upside, downside, and severe-stress scenarios to assess both potential appreciation and permanent capital risk. The discipline is embedded in our 10 Principles of Value Investing™, which guides our portfolio decisions and directs us toward financially sound companies with durable economics that can be purchased at attractive valuations.
Attribution Analysis
During the quarter, our Strategy returned -2.96%, versus the 2.31% gain for the Russell 3000® Value Index. Security selection in the Technology sector was responsible for a majority of that underperformance.
The annual FTSE Russell index rebalance took place in late June and materially changed the composition of Technology sector constituents. Most impactful were the additions of Microsoft and Apple to our benchmark because they were two of the three biggest contributors to the Russell 3000® Value Index’s performance in the third quarter. We admire both companies, but we don’t view either as materially undervalued.
Stock selection for our Strategy was weakest among the absolute largest-capitalization stocks because we don’t own Microsoft or Apple. By contrast, our stock selection was more effective among smaller- to mid-cap stocks under $15 billion in market cap.
Portfolio Activity
Bentley Systems (BSY), a newly initiated position during the quarter, is an example of a stock getting heavily discounted by a negative top-down industry narrative, with defensible and compelling long-term prospects. To be clear, we are wary of the outlook for many software products, especially those that serve administrative functions and are prone to faster switching decisions in a widening competitive landscape. Our research has centered on “vertical software” companies that provide end-to-end solutions for a specific industry because domain expertise drives higher customer loyalty and switching costs.
Among the vertical software companies in our universe, we find BSY’s characteristics especially attractive from both a “moat” and opportunity perspective. The company provides engineering software for critical infrastructure around the world for public works and natural resources end markets. Over 40 years of proprietary data and deep integration has made BSY the industry standard for infrastructure modeling and simulation. Their software represents roughly five basis points (0.05%) of total project cost for mission critical infrastructure, with BSY’s engineering customers facing severe engineering labor challenges and their asset owner customers relying on BSY’s software to ensure reliability and minimize expenses while avoiding a high cost of failure. With end market demand buoyed by a need to address structural underinvestment, we expect BSY sales and free cash flow to accelerate further as customers consume more of their offerings for AI-oriented workloads.
Sometimes, opportunities can be found inside your existing portfolio—if you have the patience to find out. Case in point, Watsco (WSO), the largest wholesale distributor of HVAC and refrigeration equipment in the U.S., which was one of the biggest detractors to performance in the quarter.
The residential HVAC industry is going through a demand lull created by a combination of factors including declining new construction activity, weakening consumer financial conditions, and a pull-forward of demand caused by a refrigerant change in 2025. Watsco and the major residential HVAC equipment manufacturers underperformed following disappointing Q2 earnings results, characterized by persistent demand weakness and margin pressure associated with a lack of volume growth and tariff-induced cost volatility.
While the market is myopically focused on short-term volume headwinds, we believe WSO is positioned to benefit from technology investments that uniquely favor the industry’s juggernaut. For example, the company has a modern tech stack and a fully digitized platform unlike most of their peers. Watsco is also using AI to optimize for demand elasticity and to identify pricing outliers that can be addressed by their sales team quickly. We believe management’s investments in AI-enhanced customer service, technical support, and software development will drive margin expansion and share gains for years to come.
Recently, Watsco announced the acquisition of two separate family-run businesses. These acquisitions should increase revenue and cash flow by roughly 10%. Given the company’s unlevered balance sheet, greater cash flow generation accrues to equity holders through an increase in intrinsic value. Yet the stock trades at a free cash flow/enterprise value yield of 6%, based on 2027 cash generation.
Our biggest contributor to performance in Q3 was MarketAxess Holdings (MKTX), which operates the largest corporate bond e-trading platform in the U.S.
In the prior quarter, this stock was one of our biggest detractors, as heavy primary bond issuance volume and tighter credit spreads temporarily diverted trading volume away from MKTX's core secondary market. Yet we remained committed to the business for reasons highlighted in our Q2 letter. In late July, competitor Intercontinental Exchange, Inc. announced its intent to buy MKTX for $167 per share in cash representing a 47% premium relative where shares traded at the end of Q2.
The market can change its mind quickly, as the past three months demonstrated. Rather than trying to anticipate the next headline or market narrative, we believe investors are better served by looking past the top-down noise and analyzing businesses from the bottom up. We remain focused on identifying companies where the range of potential outcomes offers an attractive balance of upside opportunity and downside protection, guided by our 10 Principles of Value Investing™. Markets will continue to fluctuate; our process will not.
We are grateful for your continued trust.
9/30/2026
Scroll over to view complete data
| Since Inception (%) | 10-Year (%) | 5-Year (%) | 3-Year (%) | 1-Year (%) | YTD (%) | QTD (%) | |
|---|---|---|---|---|---|---|---|
| Opportunistic Value Equity Composite (Net of Advisory Fees)** | 10.16 | 10.74 | 10.51 | 14.38 | 15.46 | 14.15 | -2.61 |
| Opportunistic Value Equity Composite (Net of Bundled Fees) | 8.19 | 8.94 | 8.99 | 12.83 | 13.88 | 12.98 | -2.96 |
| Russell 3000® Value | 8.39 | 11.31 | 11.68 | 19.97 | 23.73 | 19.22 | 2.31 |
Source: FactSet Research Systems Inc., Russell Investment Group, and Heartland Advisors, Inc.
*Yearly and quarterly returns are not annualized. The Strategy's inception date is 9/30/1999.
**Shown as supplemental information.
The US Dollar is the currency used to express performance. Returns are presented net of advisory fees and net of bundled fees and include the reinvestment of all income. The returns net of bundled fees were calculated by subtracting the highest applicable sponsor portion of the separately managed wrap account fee from the net of advisor fees return.


©2026 Heartland Advisors | 790 N. Water Street, Suite 1200, Milwaukee, WI 53202 | Business Office: 414-347-7777 | Financial Professionals: 888-505-5180 | Individual Investors: 800-432-7856
Past performance does not guarantee future results.
In addition to stocks of large companies, the Opportunistic Value Equity Strategy invests in stocks of small- and mid-cap companies that are generally less liquid than large companies. The performance of these holdings generally will increase the volatility of the strategy’s returns.
Value investments are subject to the risk that their intrinsic value may not be recognized by the broad market.
Heartland Advisors, Inc. (the "Firm") claims compliance with the Global Investment Performance Standards (GIPS®). The Firm is a wholly owned subsidiary of Heartland Holdings, Inc., and is registered with the Securities and Exchange Commission. For a complete list and description of Heartland Advisors composites and/or a presentation that adheres to the GIPS® standards, contact the Institutional Sales Team at Heartland Advisors, Inc. at the address listed below.
As of 9/30/2026, Bentley Systems Inc. (Class B) (BSY), MarketAccess Holding, Inc. (MKTX), and Watsco Inc. (WSO) represented 1.13%, 2.28%, and 2.35% of the Opportunistic Value Equity Composite’s net assets, respectively. Apple Corporation (AAPL), Meta Platforms, Inc. (META), Microsoft Corporation (MSFT) and Nvidia Corporation (NVDA) are unowned in the Opportunistic Value Equity Strategy.
The future performance of any specific investment or strategy (including the investments discussed above) should not be assumed to be profitable or equal to past results. The performance of the holdings discussed above may have been the result of unique market circumstances that are no longer relevant. The holdings identified above do not represent all of the securities purchased, sold or recommended for the Advisor’s clients.
Statements regarding securities are not recommendations to buy or sell.
Portfolio holdings are subject to change. Current and future portfolio holdings are subject to risk.
GIPS® is a registered trademark of CFA Institute. CFA Institute does not endorse or promote this organization, nor does it warrant the accuracy or quality of the content contained herein.
Separately managed accounts and related investment advisory services are provided by Heartland Advisors, Inc., a federally registered investment advisor. ALPS Distributors, Inc., is not affiliated with Heartland Advisors, Inc.
The statements and opinions expressed in this article are those of the presenter(s). Any discussion of investments and investment strategies represents the presenters’ views as of the date created and are subject to change without notice. The opinions expressed are for general information only and are not intended to provide specific advice or recommendations for any individual. The specific securities discussed, which are intended to illustrate the advisor’s investment style, do not represent all of the securities purchased, sold, or recommended by the advisor for client accounts, and the reader should not assume that an investment in these securities was or would be profitable in the future. Certain security valuations and forward estimates are based on Heartland Advisors’ calculations. Any forecasts may not prove to be true.
Economic predictions are based on estimates and are subject to change.
There is no guarantee that a particular investment strategy will be successful.
Sector and Industry classifications are sourced from GICS®.The Global Industry Classification Standard (GICS®) is the exclusive intellectual property of MSCI Inc. (MSCI) and S&P Global Market Intelligence (“S&P”). Neither MSCI, S&P, their affiliates, nor any of their third party providers (“GICS Parties”) makes any representations or warranties, express or implied, with respect to GICS or the results to be obtained by the use thereof, and expressly disclaim all warranties, including warranties of accuracy, completeness, merchantability and fitness for a particular purpose. The GICS Parties shall not have any liability for any direct, indirect, special, punitive, consequential or any other damages (including lost profits) even if notified of such damages.
Heartland Advisors defines market cap ranges by the following indices: micro-cap by the Russell Microcap®, small-cap by the Russell 2000®, mid-cap by the Russell Midcap®, large-cap by the Russell Top 200®.
Because of ongoing market volatility, performance may be subject to substantial short-term changes.
Dividends are not guaranteed and a company’s future ability to pay dividends may be limited. A company currently paying dividends may cease paying dividends at any time.
In certain cases, dividends and earnings are reinvested.
There is no assurance that dividend-paying stocks will mitigate volatility.
CFA® is a registered trademark owned by the CFA Institute.
Russell Investment Group is the source and owner of the trademarks, service marks and copyrights related to the Russell Indices. Russell® is a trademark of the Frank Russell Investment Group.
Data sourced from FactSet: Copyright 2026 FactSet Research Systems Inc., FactSet Fundamentals. All rights reserved.
Heartland’s investing glossary provides definitions for several terms used on this page.
Artificial intelligence (AI) is intelligence—perceiving, synthesizing, and inferring information—demonstrated by computers, as opposed to intelligence displayed by humans or by other animals. Enterprise Value (EV) is the entire economic value of a company. Free Cash Flow is the amount of cash a company has after expenses, debt service, capital expenditures, and dividends. The higher the free cash flow, the stronger the company’s balance sheet. Gross Domestic Product (GDP) is the monetary value of all the finished goods and services produced within a country’s borders in a specific time period, though GDP is usually calculated on an annual basis. Intrinsic Value is the actual value of a company or an asset based on an underlying perception of its true value including all aspects of the business, in terms of both tangible and intangible factors. This value may or may not be the same as the current market value. Margin of Safety is a principle of investing in which an investor only purchases securities when the market price is significantly below its intrinsic value. Operating Earnings is profit earned after subtracting from revenues those expenses that are directly associated with operating the business, such as cost of goods sold, administration and marketing, depreciation and other general operating costs. Russell Investment Group is the source and owner of the trademarks, service marks and copyrights related to the Russell Indices. Russell® is a trademark of the Russell Investment Group. Russell 2000® Index includes the 2000 firms from the Russell 3000® Index with the smallest market capitalizations. All indices are unmanaged. It is not possible to invest directly in an index. Russell 3000® Value Index measures the performance of those Russell 3000® Index companies with lower price/book ratios and lower forecasted growth characteristics. S&P 500 Index is an index of 500 U.S. stocks chosen for market size, liquidity and industry group representation and is a widely used U.S. equity benchmark. All indices are unmanaged. It is not possible to invest directly in an index. Treasury Yield is the effective rate of interest paid on a debt obligation issued by the U.S. Treasury for a specified term. Volatility is a statistical measure of the dispersion of returns for a given security or market index which can either be measured by using the standard deviation or variance between returns from that same security or market index. Commonly, the higher the volatility, the riskier the security. 10 Principles of Value Investing™ consist of the following criteria for selecting securities: (1) catalyst for recognition; (2) low price in relation to earnings; (3) low price in relation to cash flow; (4) low price in relation to book value; (5) financial soundness; (6) positive earnings dynamics; (7) sound business strategy; (8) capable management and insider ownership; (9) value of company; and (10) positive technical analysis.